The Centre for Policy Dialogue (CPD), a private research organization, says that while the new government’s first six months in office have brought some positive changes, negative trends still dominate the path toward economic recovery. The think tank’s assessment found some improvement in inflation and foreign currency reserves, but said concerns remain over revenue collection, investment, industrial output, employment and the energy situation.
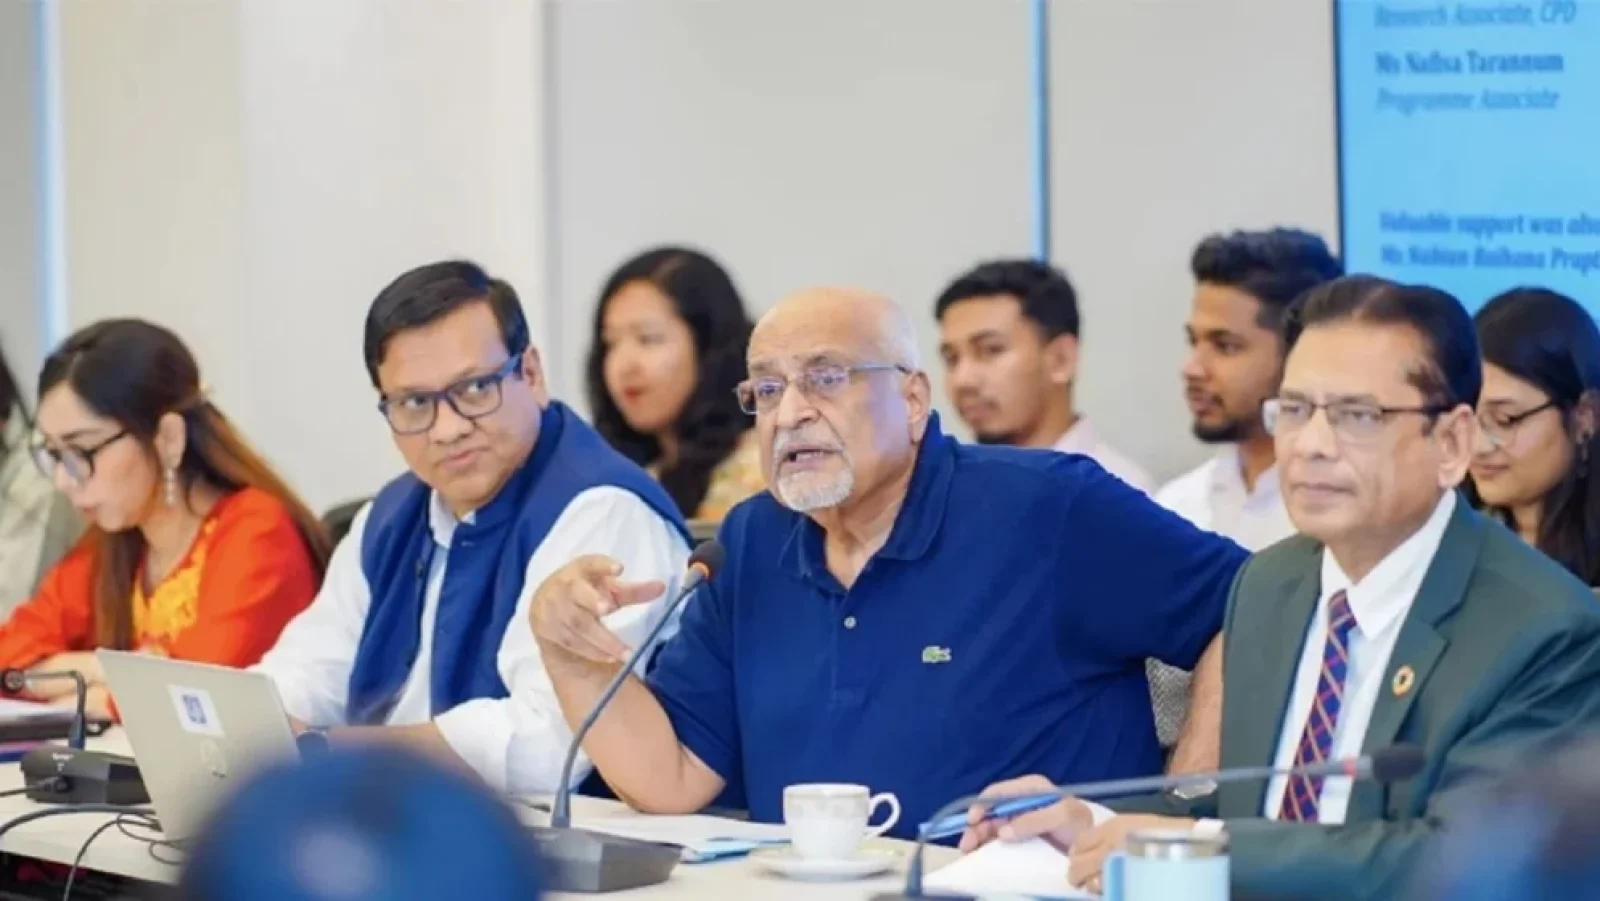
CPD Distinguished Fellow Dr Debapriya Bhattacharya presented the organization’s review of the new government’s first 180 days at a media dialogue held in the capital Monday, August 24. He said the government’s first six months present a mixed picture overall, but one weighted toward negative trends, with much of the underlying problems structural in nature.
According to Dr Bhattacharya’s presentation, the assessment reviewed a total of 362 observations across nine sectors — governance and administration, public financial management, industry and trade, banking and the financial sector, energy and transport, agriculture, education, health, and social protection. The review focused on actions actually taken, rather than mere announcements.
Some relief on inflation, but living costs remain high
CPD’s review found that overall inflation fell from 9.1% to 8.3% between February and July, while food inflation fell from 9.3% to 7.2% over the same period.
But CPD said the high cost of daily essentials means ordinary people’s cost of living remains elevated, and that with real wage growth still negative, falling inflation has not translated into the expected improvement in people’s purchasing power.
Concerns over revenue collection and investment
CPD identified weak revenue collection as one of the biggest challenges on the path to economic recovery. According to the organization, overall tax revenue growth fell from 12.3% to 4.9% between March and May, raising concerns that the current fiscal year’s revenue target may be difficult to achieve.
CPD forecast a revenue shortfall of roughly 130,000 to 140,000 crore taka (1.3 to 1.4 trillion taka) for the 2026-27 fiscal year, which could increase pressure to cut development spending, particularly under the Annual Development Programme (ADP). However, the organization recommended protecting allocations for critical sectors such as education, health and social protection.
CPD also said the investment situation is not satisfactory. Private sector credit growth fell from 6% to 4.5% between February and June, while growth in letters of credit opened for capital machinery imports turned from positive to negative over the same period. Net foreign investment also declined.
CPD said none of these indicators point to any clear sign of a swift recovery in private investment.
Gas crisis disrupting industrial output
CPD views the ongoing gas crisis as a major risk to industry and the broader economy. The organization said gas-dependent industries have suffered due to technical problems at the Moheshkhali LNG terminals, difficulties securing alternative LNG cargoes, and weaknesses in supply planning.
Sectors including textiles, steel, paper, particleboard and ceramics have all felt the impact. Growth in both the general industrial production index and the manufacturing index fell to zero between March and April, while industrial gas consumption also declined over the same period.
To address the situation, CPD recommended time-bound domestic gas exploration, strategic energy stockpiling, diversifying energy sources, and reviewing power purchase agreements to ease the subsidy burden.
Banking reforms under way, but questions remain over confidence
CPD identified several government initiatives in the banking and financial sector as positive, including the merger of five troubled Islami banks and the application of the Bank Resolution Act to distressed financial institutions.
However, the organization raised concerns about Bangladesh Bank’s independence, senior-level appointments, and structural reform of the banking sector. CPD said a full roadmap is needed for the sector’s recovery.
Reserves rise, but external pressures persist
CPD said that while there has been some positive progress in the external sector, the overall situation is not yet fully reassuring. According to the organization, foreign currency reserves under the BPM6 accounting standard rose from $30.1 billion to $32.3 billion between February 19 and August 12.
But over the same period, the trade deficit widened and the current account balance moved from surplus into deficit. Growth in remittances and overseas employment also declined. CPD views the ongoing conflict in the Middle East as one of the key factors behind this.
Why is economic recovery moving so slowly?
CPD identified several reasons behind the slow pace of economic recovery, including the absence of a coordinated, comprehensive reform program; a weak revenue and fiscal structure; pressure on global energy and commodity prices from the war in the Middle East; the influence of powerful vested-interest groups; the law-and-order situation; and a lack of the expected improvement in institutional capacity.
CPD said economic recovery cannot be judged by falling inflation alone. Alongside stability in inflation, the exchange rate and interest rates, it said, visible improvement in GDP growth, rising investment and new job creation are essential.
Call for a coordinated reform program
To support a sustained economic recovery, CPD recommended preparing a realistic “core budget” covering the period from October to June, based on real-time data and a credible fiscal framework.
The organization also emphasized implementing a coordinated reform package across key areas including energy, banking reform, revenue administration, rationalizing development spending, security, supply systems and digitalization. It called for effective coordination between the government and various institutions, and for ensuring regular accountability to parliament.
In its overall assessment, CPD said that while the government has taken some reform-oriented and welfare-focused steps in its first six months, it has yet to overcome the economy’s core structural weaknesses. As a result, the organization said, the government’s biggest challenge going forward is the swift implementation of a coordinated, realistic and accountable reform program, rather than isolated initiatives.
বাংলায় মূল প্রতিবেদন পড়ুন · Read the original Bengali report